We are sharing the latest version of the cargo report.
The following highlights are worth noting:
- DGT Current Update — as of 5 November:
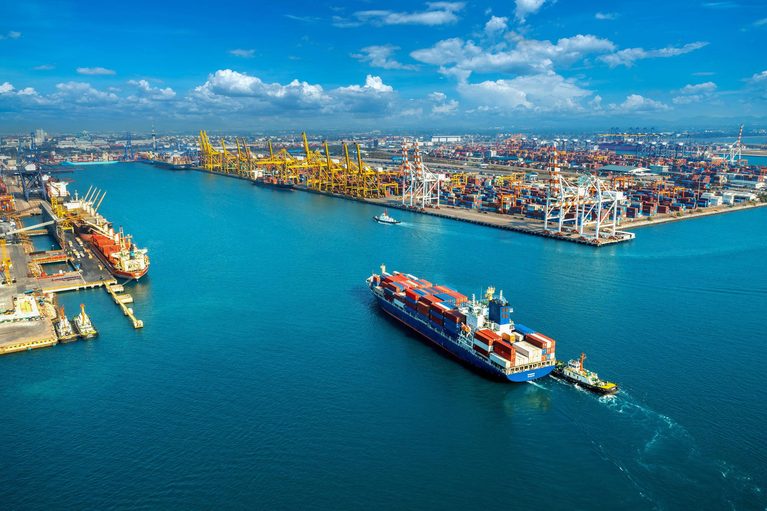
Waterside performance improved: throughput increased +12% to 34,976 TEUs, while average anchorage time eased to 266 hours.
The vessel backlog remains the principal concern: the queue reached 15 vessels on 3 November and remained at 13 on 5 November, with current conditions adding around 20 days to affected supply chains.
DGT has stabilised, but not recovered: yard conditions remain manageable, although stack occupancy has risen to 70%; importantly, the stronger weekly throughput has not yet produced sustained backlog reduction.
- International Shipping – Capacity, Freight Rates and Market Developments:
Unprecedented capacity deployment:Sea-Intelligence reports record October–November capacity on major East–West trade lanes, despite persistent congestion and vessel bunching.
Record containership orderbook: New orders reached 6.4 million TEU in 2026, bringing the orderbook to 16.6 million TEU (47.8% of the active fleet), raising substantial overcapacity concerns.
Diverging freight markets:Drewry’s WCI declined by -3.4% to US$4,429/FEU, while Harpex increased by +2.4% to 2,585 points. Renewed Strait of Hormuz security risks added pressure to tanker markets.
- International Air Cargo – Demand Growth and Pricing Pressures:
Stronger global demand: IATA reports September air cargo growth of +7.7% (y/y), with international demand +8.6% against capacity growth of just +2.7%.
Freight rates continue climbing:WorldACD reports spot rates increasing by +5% (w/w) to $3.80/kg (+38%, y/y), despite declining volumes (-2%).
Regional divergence persists: Asia–US volumes increased by +9% (y/y), compared with -16% on Asia–Europe, while Arabian Gulf capacity remained -19% below pre-conflict levels.