
Welcome to another Logistics News Update.
Durban Gateway Terminal may have a solution to the booking problem, they are looking at introducing a new booking system, this will be welcomed if it works. At the moment, we are looking at 11 days delay (published) but it could be far worse as the operators say it could be double that.
This week’s logistics environment remains challenging, with Durban Gateway Terminal (DGT) still operating about 30.5% below normal throughput levels, despite a shorter vessel queue and proposed truck booking system improvements aimed at easing congestion. Agricultural exporters and importers are being urged to confirm terminal acceptance, container availability, and transport bookings before committing to delivery schedules, particularly for perishable cargo. Temporary storage charge relief may reduce some costs, but businesses should obtain written confirmation as storage waivers do not automatically cover demurrage, detention, or transporter charges.
Elsewhere, Transnet reported improved annual rail volumes although infrastructure crime continues to impact reliability, OR Tambo’s jet fuel mitigation plan has reduced immediate air cargo concerns, and global container freight rates remain relatively stable despite route specific fluctuations. Agricultural bodies continue pushing for improved BRICS market access, while businesses are advised to closely monitor DGT recovery efforts, rail corridor performance, port delays, airport operations, freight rate movements, and route specific service reliability when planning shipments and protecting margins.
On the international front, Shanghai is still clearing the backlog created by the typhoon disruption that suspended container operations at affected terminals from late August. Vessel berthing delays, omitted port calls and revised sailing schedules continue to affect shipments there, and the operational update supplied to TSI indicates that these delays could run into late September. This comes as carriers’ trim capacity ahead of China’s Golden Week holiday, with Drewry forecasting 79 blank sailings across the major East to West trades between 14 September and 18 October. Global container rates remain broadly stable overall; that stability does not always translate into dependable departures or available space on an individual shipment.
Agri & Transport Summary
Durban recovery remains important for agricultural exports: Freight News reported on 11 September, citing SAAFF, that Durban Gateway Terminal’s average daily container throughput over the four weeks to 10 September remained 30.5% below the preceding four-month average. Although the vessel queue shortened between 7 and 10 September, SAAFF cautioned that this had not yet produced sustained recovery. For agricultural exporters, the practical implication is to confirm terminal acceptance and loading arrangements before dispatching temperature-sensitive cargo, particularly where a missed sailing could affect product quality and market arrival dates.
Booking changes offer a potential improvement for transporters: A separate Freight News report said DGT had developed changes to its truck-slot booking system for stakeholder comment before implementation. SAFLA and the Road Freight Association also reported that terminal storage charges were being waived while the operational difficulties continued. These developments could help reduce uncertainty and cost exposure, but transporters still need workable bookings matched to terminal capacity. Businesses should obtain written confirmation of any charge relief applicable to their containers before adjusting shipment costs.
Agricultural organisations push for broader export opportunities: AgriSA and Agbiz called on 10 September for lower trade barriers and stronger agricultural trade across BRICS markets. Their proposals include closer regulatory cooperation and reducing unnecessary duplication in plant- and animal-health requirements. This is a call for further market-opening measures, rather than confirmation of new access. For exporters, the commercial opportunity will depend on product-specific approvals, competitive delivery costs, and dependable routes to buyers.
What to monitor: DGT booking-system implementation, confirmed export acceptance, vessel loading windows, written storage-waiver terms, and commodity-specific developments in BRICS market access. For perishable cargo, align cold-store dispatch and transport bookings with confirmed terminal arrangements to protect remaining shelf life.
Logistics & Trade Headlines
- DGT prepares booking changes as transporters await more reliable access: Freight News reported on 11 September that Durban Gateway Terminal had developed a revised slot-booking solution for stakeholder comment before implementation. Industry associations also reported temporary storage-charge relief during the operational difficulties. For cargo owners and transporters, the next test is whether these measures improve container collection and reduce truck standing time. Written confirmation of applicable relief remains important when reconciling shipment costs.
- Transnet’s annual rail volumes improve, while infrastructure crime remains costly: Transnet moved 167.9 million tonnes by rail in its 2025/26 financial year, up from 160.1 million tonnes, but below its 180 million-tonne target, according to Freight News’s coverage of the group’s results. Theft and vandalism losses approached R2 billion. The annual improvement is encouraging, although businesses planning rail movements still need to assess service availability and reliability on their specific corridors.
- OR Tambo fuel mitigation provides reassurance for air cargo: ACSA said at its 9 September results announcement that a coordinated supply plan was in place to manage the Natref-related jet-fuel shortfall, with OR Tambo not currently facing a supply disruption. Freight News reported that stakeholders would continue monitoring whether expected fuel deliveries arrived as planned. This supports confidence in time-sensitive airfreight planning, while keeping fuel replenishment and airline operational updates on the watch list.
- SARS amends rebate exclusions for certain steel anti-dumping duties: SARS published Notice R.7902 on 11 September, identifying rebate items excluded from applicable anti-dumping duties on specified steel sections from China and Thailand. The amendment applies retrospectively from 19 March 2026. Affected importers should have their clearing agents check the precise product scope, rebate eligibility, and treatment of earlier entries before revising landed costs or assuming an entitlement to relief.
- Global container benchmark remains broadly stable, with routes moving differently: Drewry’s World Container Index stood at US$4 476 per 40ft container on 10 September. Shanghai–Los Angeles and Shanghai–New York rates increased, while Shanghai–Rotterdam and Shanghai–Genoa rates declined. For South African businesses, the implication is to assess the actual route and carrier offer when budgeting freight. This index measures selected major East–West trades and is a dated market benchmark, rather than a South African route quotation.
- Traxtion plans asset identification to support future rail financing: Traxtion plans to obtain internationally recognised identification numbers for its R3.4 billion locomotive and wagon portfolio, according to Freight News. The company said the initiative could support financing and leasing by improving asset identification and reducing uncertainty for funders. Its commercial significance is the potential to support investment in rolling stock as private rail participation develops; additional operating capacity will depend on subsequent investment and deployment.
- SolitAir expands cargo connections between Dubai and West Africa: SolitAir has launched freight services between Dubai and Accra, adding another connection for Ghanaian exports and international inbound cargo. The airline identified food products and perishables among the cargo opportunities. For businesses trading across African markets, the service adds a routing option to investigate, with onward connections, handling arrangements and total transit time requiring confirmation for each shipment.
What to monitor:
DGT booking implementation and charge-relief terms, corridor-specific rail performance, OR Tambo fuel deliveries, eligibility under the SARS steel amendment, route-specific freight quotations and whether new air-cargo connections offer workable delivery times.
Let’s Learn, why a storage waiver may not stop every container charge
When a container is delayed, several charges can accumulate along its journey, understanding what each charge covers helps businesses assess their exposure and establish exactly what has been waived.
Storage generally relates to the use of space at a terminal or depot beyond the applicable free period. Demurrage generally relates to keeping the shipping line’s container inside the terminal beyond its free period, while detention generally relates to keeping that container outside the terminal beyond the agreed allowance. Some carriers combine demurrage and detention into one period covering both locations. The applicable booking terms determine which arrangement applies. Maersk, detention and demurrage definitions for an import shipment, this means collecting the container may end one charging period while starting another. Delivering the goods to the customer does not necessarily finish the process: the empty container still needs to reach the agreed return location. Hapag-Lloyd’s South African import detention terms, for example, measure the period from collection to empty-container return and count calendar days. Hapag-Lloyd, South Africa terms effective 1 July 2026
Where businesses get caught
A business may hear that “storage has been waived” and assume that all delay-related costs have stopped. The practical question is which charge the relief covers, who authorised it, which containers qualify and which dates are included. A terminal waiver should not be assumed to cover a shipping line’s equipment charges or a transporter’s standing-time invoice. Another common misunderstanding is that “seven free days” describes one universal allowance. Businesses need to establish the relevant charge, the event that starts the clock, whether weekends count and the event that stops it.
A hypothetical example
An importer receives written confirmation that terminal storage has been waived for a delayed container. Under its separate carrier agreement, however, two chargeable demurrage days remain at an assumed R900 per day. After collection, the empty container is returned one chargeable day late, attracting an assumed R700 detention charge. The importer would still face R2 500 in carrier charges, despite the terminal storage waiver. These figures are illustrative only and are not current tariffs or an assessment of DGT’s relief arrangements.
Practical takeaway
Keep a simple record for each container showing the applicable free periods, last free dates, collection and return events and written waivers. Before closing the shipment cost, reconcile the terminal, carrier, and transporter charges separately. This makes it easier to identify an incorrect invoice, support a dispute and understand the remaining cost exposure.
NEWS
DGT recovery: turning booking changes and cost relief into reliable cargo movement
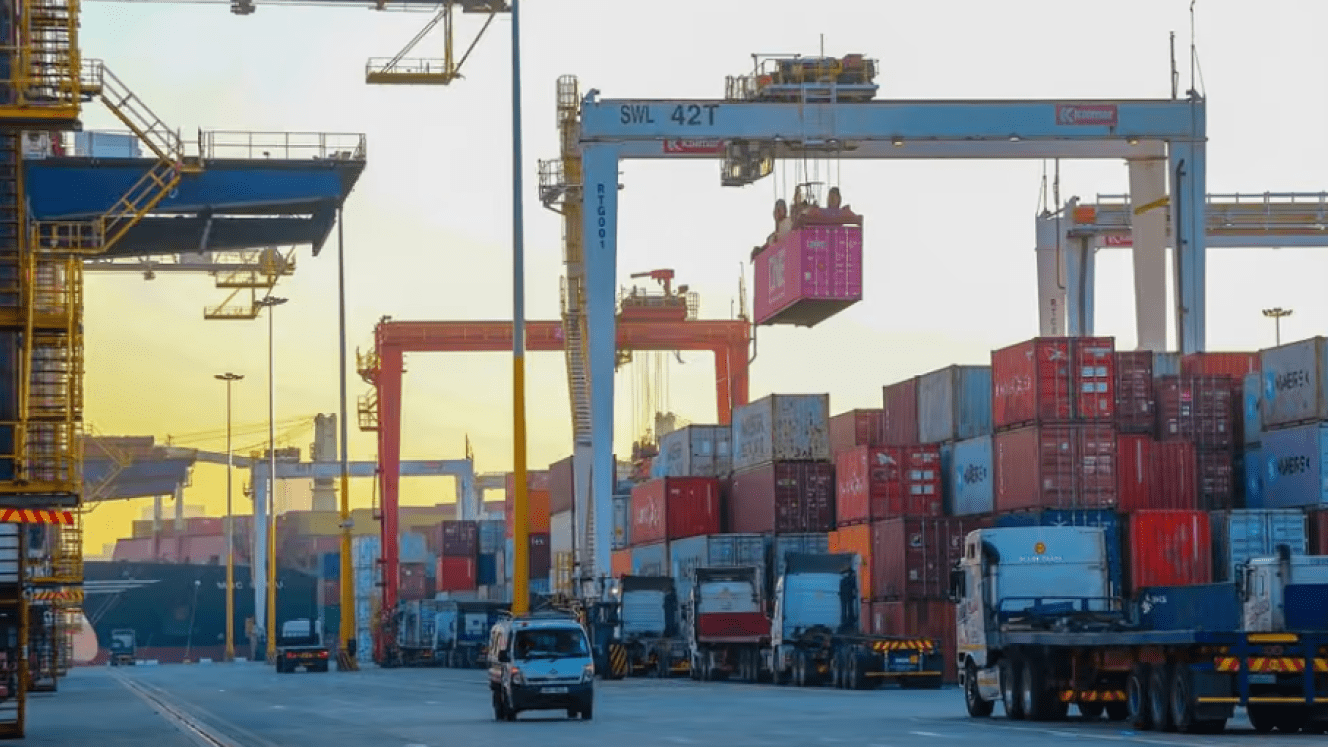
DGT throughput remained 30.5% below its recent average, as vessel delays, container diversions and reefer capacity pressures persisted.
Source: Container Management
Durban Gateway Terminal’s recovery efforts gained a potentially useful development this week, with industry associations reporting a proposed slot-booking solution and temporary relief from terminal storage charges. For businesses carrying the cost of delayed cargo, these measures offer some reassurance, although their value will ultimately depend on whether containers move more predictably through the terminal. Freight News reported on 11 September that the South African Freight and Logistics Association and Road Freight Association had met with DGT and ICTSI. According to the associations, the booking changes would be circulated for stakeholder comment before implementation. They also reported accelerated equipment maintenance and the introduction of generators to reduce disruption from power interruptions. The booking solution therefore remained a proposed operational improvement at the time of reporting.
The operational figures explain why sustained recovery remains important. SAAFF’s assessment showed average daily throughput of 3 672 twenty-foot equivalent units (TEUs) between 14 August and 10 September, compared with 5 286 TEUs during the preceding four months, a reduction of approximately 30.5%. The anchorage queue fell from ten vessels on 7 September to five on 10 September, while approximately 11 550 containers had been diverted. However, SAAFF cautioned that the shorter queue had not yet translated into sustained terminal recovery. These developments need to be considered together. A shorter vessel queue can reflect both cargo diversion and improved handling, so it cannot establish recovery on its own. Likewise, a booking-system change can improve coordination, but its practical success depends on equipment, yard capacity and container readiness supporting the appointments offered to transporters.
What this means for clients
For importers, the commercial objective is to turn a confirmed collection into a dependable delivery. Before committing stock to a customer or production schedule, businesses should establish whether the container is available, released and supported by a workable transport booking. When those steps remain uncertain, inventory stays tied up and the expected receipt of sales proceeds may move further out. For agricultural exporters, dispatch decisions need to match terminal acceptance and vessel loading arrangements. A confirmed ocean booking is one part of that plan; cold-store handovers, transport timing and refrigerated-container handling must also align. The commercial concern extends to remaining shelf life and the ability to reach the buyer’s intended selling window.
The reported storage relief could reduce part of the financial burden. Businesses should nevertheless obtain written confirmation of the containers, dates and charges covered before treating an invoice as waived. Keeping collection attempts, booking records and correspondence together will also make outstanding charges easier to reconcile.
What to monitor: Publication and implementation of the revised booking arrangements, consistency of daily throughput, successful truck collections, equipment availability, refrigerated-cargo acceptance, and the written scope of storage relief. The clearest evidence of recovery will be sustained improvement across these measures, supported by more dependable delivery and loading outcomes.
Port Operations Update:
- Durban 11 days
- Cape Town 5 days
- Coega 2 days
- Port Elizabeth 1 day
Durban shows the greatest delay exposure among these four ports, followed by Cape Town. Coega and Port Elizabeth show lower indicators. These readings are planning indicators, not guaranteed waiting times or confirmation that a particular container is available for collection.
Durban :
Confirm vessel position, container release, and collection bookings before promising delivery. For refrigerated exports, align dispatch with confirmed terminal acceptance and loading arrangements.
Cape Town :
Check the vessel’s latest arrival estimate and terminal stack window before arranging transport, particularly for time-sensitive exports.
Coega / Ngqura :
When considering an alternative routing, confirm the onward sailing, handling arrangements, and inland transport cost.
Port Elizabeth :
Check service frequency and final delivery arrangements alongside the lower congestion indicator when assessing the route.
What to monitor:
Changes in these readings, current carrier and terminal notices, confirmed export stack dates and actual collection availability.
Key Highlights from Last Week’s Discussions – September 6th
Source: BUSA, SAAFF, and global logistics data
Port Operations
South African container terminals handled 84 435 TEUs during the week of 17 to 23 August, an increase of 1% from the previous week’s 83 471 TEUs. Average daily throughput increased to 12 062 TEUs. Terminal performance was mixed. Durban Gateway Terminal handled 26 162 TEUs, up 1% week on week. Durban Pier 1 handled 16 570 TEUs, up 16%. Cape Town Container Terminal handled 15 095 TEUs, down 1%. Ngqura handled 15 940 TEUs, down 5%and Port Elizabeth handled 5 080 TEUs, up 11%. The key point is that the national number improved only slightly, while Durban Gateway Terminal remained the main operational concern. DGT is showing signs of recovery, but the terminal is still working through the effects of the NAVIS N4 transition, yard pressure, equipment constraints, vessel delays, and landside evacuation challenges.
Key Insight: National container throughput improved marginally, but the recovery remains uneven. Durban Gateway Terminal still needs to be managed separately because a small increase in weekly TEUs does not mean terminal fluidity has normalised.
Rail and Inland Movement
Reported Durban ConCor movements fell 30% to 1 064 containers. BUSA/SAAFF attributed this partly to incomplete data, alongside maintenance closures and DGT disruption.
Key Insight: The reported decline needs to be treated cautiously until the data is complete.
Air Cargo
OR Tambo handled approximately 6 536 tonnes, with imports increasing and exports declining. Inbound figures remained subject to reconciliation. Separately, freight-warehouse access works were scheduled from 9 September through late October.
Key Insight: Collection and delivery access needs checking alongside flight availability.
Road and Border Crossings:
Lebombo truck volumes fell 9% to 1 369 vehicles daily. Average queue time improved to 4.7 hours, while processing time increased to 4.4 hours.
Key Insight: Shorter queues coincided with lower volumes; processing itself took longer.
Global Shipping Context
BUSA/SAAFF highlighted Asian port congestion and Middle Eastern route disruption as constraints on shipping capacity and schedules.
Key Insight: Delays at overseas ports can affect South African cargo before it reaches local waters.
Global Freight and Air Cargo Context:
The report included Drewry’s 10 September container benchmark of US$4 476 per 40ft. WorldACD’s August figures showed global air-cargo chargeable weight up 5% year on year and average rates up 22%.
Key Insight: These are market benchmarks, not quotations for South African shipments.
Strategic Outlook
Performance remained uneven across ports, rail, and borders. Businesses should use this retrospective report to understand trends, alongside the latest operational information when making shipment decisions.
What to monitor: Sustained cargo evacuation, revised rail and air figures, airport warehouse access, and route-specific border conditions.
Global Freight Rates – Drewry
Drewry expects overall rates to remain broadly stable in the following week, although congestion and cancelled sailings continue to affect available capacity. Intra-Asia rates edged higher: Drewry’s Intra-Asia Container Index increased 1% to US$1 323 per 40ft, reaching a record for the third consecutive week. Individual routes differed: Shanghai–Singapore declined 7%, while Shanghai–Tanjung Pelepas increased 6%.
What this means for businesses: These benchmarks help explain market direction but are not South African route quotations. When comparing offers, check the actual routing, transshipment arrangements, surcharges, free time and quotation validity.
What to monitor: Drewry’s next weekly assessment, carrier capacity changes and whether movements on Asian feeder routes affect the cost or timing of South Africa-bound cargo.
Final Thoughts
The practical priority for the week ahead is to turn logistics information into realistic delivery commitments. Where timing remains uncertain, early communication gives customers and suppliers more room to adjust production, receiving arrangements and stock plans.
- Operational: Confirm container availability, terminal acceptance, and transport bookings before committing to collection or delivery.
- Commercial: Reconcile freight, storage, and equipment charges separately, with written confirmation of any relief.
- Planning: Allow for delays where they would affect production or sales and compare alternative routes using the full delivery cost and transit time.
For agricultural businesses, dependable movement helps protect product quality and market arrival windows. For importers and transport operators, it supports better use of stock, vehicles, and working capital. Keeping these decisions aligned helps preserve both customer confidence and margins.
This week’s news was brought to you by:
FNB First Trade™ 360 — your partner in logistics and Exporters Western Cape
Sources and Further Reading
South African Logistics and Trade
- DGT develops slot-booking solution Freight News, 11 September 2026.
- DGT throughput remains 30% below recent average Freight News, 11 September 2026.
- AgriSA and Agbiz call for deeper agricultural trade across BRICS markets AgriSA, 10 September 2026.
- Theft and vandalism cost Transnet almost R2bn Freight News, 14 September 2026.
- OR Tambo fuel-supply mitigation update Freight News, 10 September 2026.
- Tariff amendments: Notice R.7902 on specified steel anti-dumping rebate exclusions SARS, published 11 September 2026.
- Traxtion plans international identification for rolling stock Freight News, 11 September 2026.
- SolitAir adds Accra to its cargo network Freight News, 11 September 2026.
Port Indicators and Freight Rates
- South Africa port congestion indicators GoComet, checked directly on 15 September 2026. Readings change as the tracker updates.
- World Container Index Drewry, assessment dated 10 September 2026.
- Intra-Asia Container Index Drewry, assessment dated 10 September 2026.
Weekly Cargo Report
- BUSA/SAAFF Cargo Movement Update #298 supplied report dated 6 September 2026, covering 31 August–6 September, with later operational updates through 10 September. Includes international market information attributed to Drewry, Linerlytica, IATA and WorldACD.
Background Reading: Let’s Learn
- Definitions and terms for storage, demurrage, detention and free time — Maersk, checked 15 September 2026.
- South African detention terms — Hapag-Lloyd, effective 1 July 2026. Used to explain charging periods; shipment-specific terms must be confirmed.
Disclaimer: The information provided in this newsletter is based on reliable sources and has been carefully verified. This Logistics News is distributed free of charge. If you wish to unsubscribe from our mailing list, please reply to this email with “unsubscribe” in the subject line. Please note that all content is adapted or directly quoted from its sources. We take no responsibility for any inaccurate reporting; we are only adapting the news for you.
“This information contained herein is being made available for indicative purposes only and does not purport to be comprehensive as the information may have been obtained from publicly available sources that have not been verified by FirstRand Bank Limited (“FRB”) or any other person. No representation or warranty, express, implied or by omission, is or will be given by FRB, its affiliates or their respective directors, officers, employees, agents, advisers, representatives or any other person as to the adequacy, reasonableness, accuracy or completeness of this information. No responsibility or liability is accepted for the accuracy or sufficiency thereof, or for any errors, omissions or misstatements, negligent or otherwise, relating thereto. In particular, but without limitation, no representation or warranty, express or implied, is given as to the achievement or reasonableness of, and no reliance should be placed on, any projections, targets, estimates or forecasts and nothing contained herein should be relied on as a promise or representation as to the past or future. FRB does not undertake any obligation to provide any additional information or to update the information contained herein or to correct any inaccuracies that may become apparent. The receipt of this information by any person is not to be taken as constituting the giving of any advice by FRB to any such person, nor to constitute such person a client of FRB.”